Overview
In Part 1 of our inflation series, we discussed how disruptions to supply and demand can have a sharp short-term impact on inflation, as happened after the onset of COVID-19 and the war in Eastern Europe. In Part 2, we explored how globalisation has historically pushed prices down and whether the political environment suggests that trend is ending. In Part 3, we examine how technology has transformed production and, in turn, prices, making it the most persistent force in the inflation story.
Technological progress has driven economic growth since the Industrial Revolution. As technology advances, production becomes more efficient and the cost of making goods and delivering services falls. Competition then passes those savings on to buyers. The result is a desirable form of deflation: societies consume more for less, and resources are freed for new kinds of production.
The mechanism
The chain is straightforward. A new technology lets a firm produce the same output with less labour, energy or material. Its unit cost falls. If the market is competitive, rivals adopt the same technology or lose share, and the price falls towards the new, lower cost. The buyer keeps most of the gain.
Two conditions matter. The technology has to spread, which takes time and investment. And the market has to be competitive enough that savings reach the buyer rather than staying with the producer as margin. Where either condition fails, productivity gains show up as profits rather than lower prices.
Moore’s Law
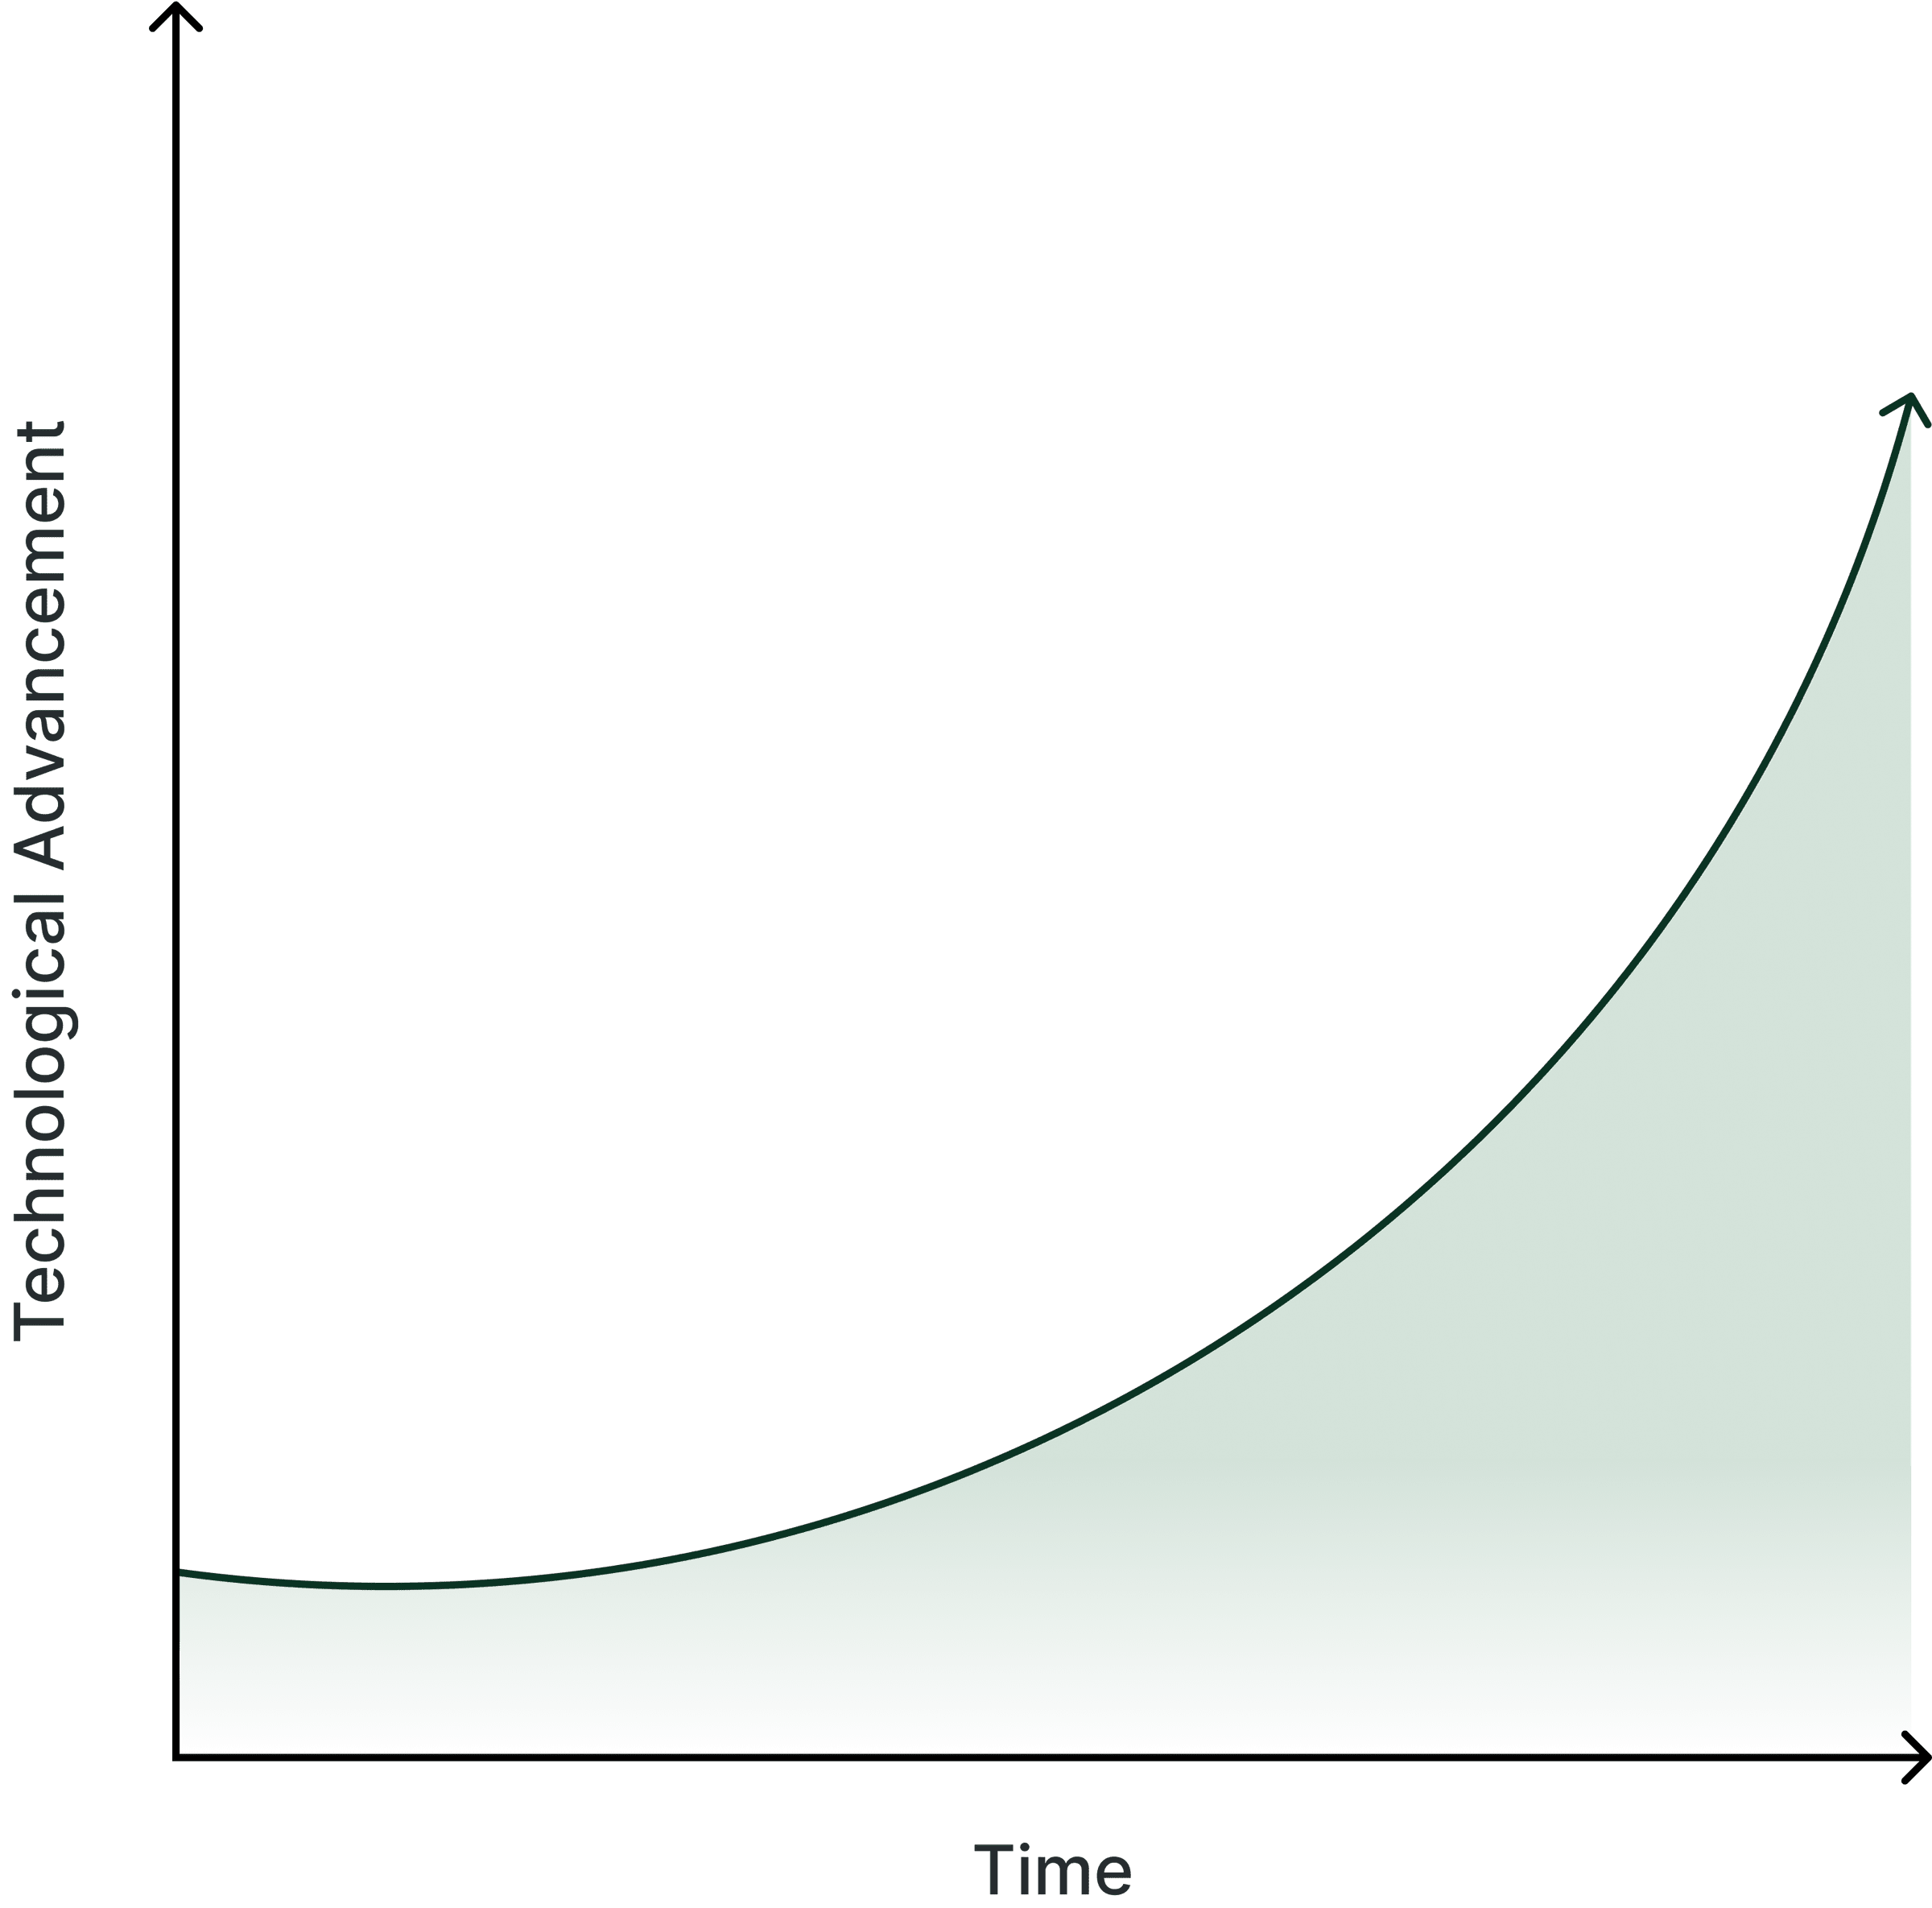
The semiconductor industry is the clearest example. Gordon Moore, who went on to co-found Intel, observed in 1965 that the number of components that could be placed on a chip was doubling at a regular pace, a rate later settled at roughly every two years. The consequence of that compounding is that each generation of chips does far more work at a similar cost, which means the cost of a unit of computing has fallen relentlessly for half a century.
Because chips sit inside almost everything, that deflation has spread well beyond computers: into telephones, cars, medical devices, logistics and finance. Much of what we now take for granted, from video calls to navigation, would have been prohibitively expensive a generation ago.
What the price data shows
The effect is visible in official statistics, and so is its unevenness. US Bureau of Labor Statistics consumer price indices, January 2000 to December 2025:
| Index (US CPI) | Change, Jan 2000 to Dec 2025 |
|---|---|
| Televisions | about −98% |
| All items | about +92% |
| College tuition and fees | about +196% |
Two caveats help read this. First, the television index is quality-adjusted: the BLS removes the value of better features from measured price changes, so much of the fall reflects how much more a set does for the money, not only a lower sticker price. That is still deflation in the sense that matters, more for less. Second, the contrast with tuition is the point. Where productivity is easy to raise, prices fall. Where a service still depends on a person’s time, such as a teacher, a doctor or an adviser, costs track wages, and prices rise. Economists call this Baumol’s cost disease. It explains why technology can be strongly deflationary in some categories while headline inflation stays positive. Past performance is not indicative of future results.
Energy is on the same curve
The same learning-curve dynamic now applies to energy, which feeds into the cost of almost everything else. According to the International Renewable Energy Agency’s Renewable Power Generation Costs in 2023, the global average cost of electricity from new utility-scale solar fell to USD 0.044 per kWh in 2023, a decline of 90% since 2010. The cost of battery storage projects fell 89% over the same period. For the Gulf, where solar resources are among the best in the world, this matters directly: cheaper generation lowers the cost base of industry, water desalination and cooling.
The next leg: AI
Artificial intelligence may extend the pattern from physical goods to cognitive work. In his essay Three Observations, OpenAI’s chief executive Sam Altman claimed that “the cost to use a given level of AI falls about 10x every 12 months.” That is a company’s claim about its own field, not an independent measurement, and it describes the cost of the technology rather than the price of anything a household buys.
The plausible channel is labour. Tasks that are expensive today because they require skilled attention, drafting, research, coding, customer service, become cheaper as software does more of them. If that happens at scale, it would put downward pressure on the prices of services, the part of the economy that technology has so far struggled to make cheaper. There are offsets. Building and powering data centres requires heavy investment and large amounts of electricity, which can push some costs up in the near term, and gains reach consumers only where competition forces them through. We discuss the investment side in Generative AI’s impact on your investments.
Good deflation and bad deflation
Not all falling prices are welcome. Productivity-driven deflation raises living standards because it comes from making more with less. Demand-driven deflation is different: when spending collapses, prices fall because buyers have disappeared, firms cut wages and jobs, and the real burden of debt rises. Expecting lower prices tomorrow, households and businesses delay spending today, which deepens the fall.
The difficulty is that the two can interact. A long run of falling prices, whatever the cause, makes holding cash look attractive. If prices are declining, cash gains purchasing power simply by sitting still. That discourages lending and investment in new production, which slows growth. This is why central banks target a small positive inflation rate rather than zero, and why they lean against deflation even when technology is its source. That is the subject of Part 4.
What this means for investors in the UAE
- Inflation is a blend, not a single number. Technology makes some things much cheaper and leaves others untouched. For most families the largest costs, housing, school fees, healthcare and travel, sit in the categories technology has made least cheap.
- Cash still loses ground. While central banks target positive inflation, cash held for the long term tends to lose purchasing power after tax and inflation. Our framework on why investing is vital sets out how much cash to hold and why.
- Diversify across the change. Technology creates winners and losers, and the winners are hard to identify in advance. A broadly diversified portfolio owns the productive economy as a whole, including the companies that adopt new technology as well as those that build it.
Technology is the long-run force pulling prices down. Supply shocks and policy can override it for years at a time, but they do not reverse it.
Frequently asked questions
How much has technology actually reduced prices?
In technology-intensive goods, a great deal. The US Bureau of Labor Statistics' quality-adjusted price index for televisions fell about 98% between January 2000 and December 2025, over a period when the all-items CPI rose about 92%. The index adjusts for quality, so much of the fall reflects how much more a television does for the same money.If technology is deflationary, why does inflation persist?
Because technology lowers costs unevenly. Goods made in factories get cheaper quickly; services that depend on people, such as education, healthcare and housing-related services, do not, and they make up a large share of household spending. Monetary policy also aims for positive inflation, as Part 4 explains.Will AI continue this trend?
It may. AI lowers the cost of tasks such as drafting, coding and customer service in the same way that machines lowered the cost of physical work. OpenAI's chief executive has claimed the cost of using a given level of AI falls about tenfold each year. Whether that shows up in consumer prices depends on competition, on how much labour cost is actually displaced, and on the energy AI itself consumes.Is deflation a good thing or a bad thing?
Productivity-driven deflation is good: consumers get more for less and resources are freed for new production. Demand-collapse deflation is bad: it encourages hoarding, raises the real burden of debt and can feed on itself, as in the Great Depression. Central banks fight the second kind, sometimes at the cost of muting the benefits of the first.What does technology-driven deflation mean for portfolios?
Two things. First, the benefits accrue unevenly across companies and sectors, which argues for broad diversification rather than concentrated bets on who will win. Second, holding cash in the hope that prices will fall is a poor strategy while central banks target positive inflation: the goods that get cheaper are rarely the ones that dominate a family's budget.
From Vault
Vault's own portfolios are built to hold through exactly this kind of move rather than trade around it.
Related reading
More on Markets & macro
- InsightInflation Part 01: An Unfortunate Mismatch between Demand & SupplyIn this series of email memos, we will explore the various factors that are driving inflation (both in the short and lon
- InsightInflation Part 02: GlobalizationDeep dive into some of the critical ways that globalization has contributed to a low inflationary environment.
- InsightInflation Part 4: Monetary Policy and the Future of InflationHow central banks steer inflation, why they target 2% rather than zero, how US policy reaches the UAE through the dirham peg, and what it means for your portfolio.