Introduction
Last verified: 22 October 2026. Competitor details below were checked against each firm’s own website and the DFSA, ADGM FSRA and UAE Central Bank registers on that date. The criteria below (regulatory framework, fiduciary alignment, fee transparency) apply equally to today’s market, but always confirm a firm’s current licence and full fee schedule directly before committing.
This page is a comparison: six firms that UAE residents most often shortlist, set against the same attributes, followed by the questions that separate them. The short answer: the firms worth meeting are regulated by the FSRA (ADGM) or the DFSA (DIFC), are paid only by the client rather than by product providers, hold your assets in your own name at a third-party custodian, and publish their fees. Whichever you shortlist, ask for the complete fee schedule in writing before the first meeting.
If you have already narrowed the field and want to know how one firm actually works with a client, our pages on private wealth management in Dubai and wealth management across the UAE set out Vault’s service, fees and regulation in full. If you are choosing an individual rather than a firm, how to choose a financial advisor in Dubai covers credentials and how the advisor is paid.
Choosing a wealth management firm or company in Dubai & UAE
When considering a wealth management firm or company in Dubai & UAE, there are several things to consider. On cost, compare the total you will actually pay, not the headline management fee — that single number is where most of the confusion in this market lives.
Private banks and traditional wealth managers typically layer charges: an annual management fee, a separate custody fee, dealing commissions on each trade, commissions on the products placed, and a spread on currency conversion. Some mandates add a performance fee on top. Emirates NBD’s published schedule for portfolio accounts, for instance, lists a 0.525% annual wealth-management fee and a separate 0.42% annual custody fee, plus 1.05% per trade on global equities and ETFs, so the sum sits well above the first figure quoted. Vault charges one management fee, tiered so the rate falls as the portfolio grows, with no entry fee, no exit fee and no performance fee. The per-firm comparisons — HSBC, Julius Baer, Emirates NBD, and all eleven side by side — set out each institution’s published position with sources.
At the other end of the market, robo-advisors are cheaper on headline fee and will stay cheaper. They allocate to model portfolios algorithmically, and for a straightforward position that is often the right answer. What an advisory relationship buys that a robo cannot is a named human advisor and a plan built around your actual circumstances — cross-border tax exposure, a concentrated business holding, school fees with dates attached, succession through the right structure — rather than an allocation to one of three risk buckets. If your situation fits a risk bucket, pay the lower fee. See Vault vs Sarwa and Vault vs StashAway for that comparison in detail.
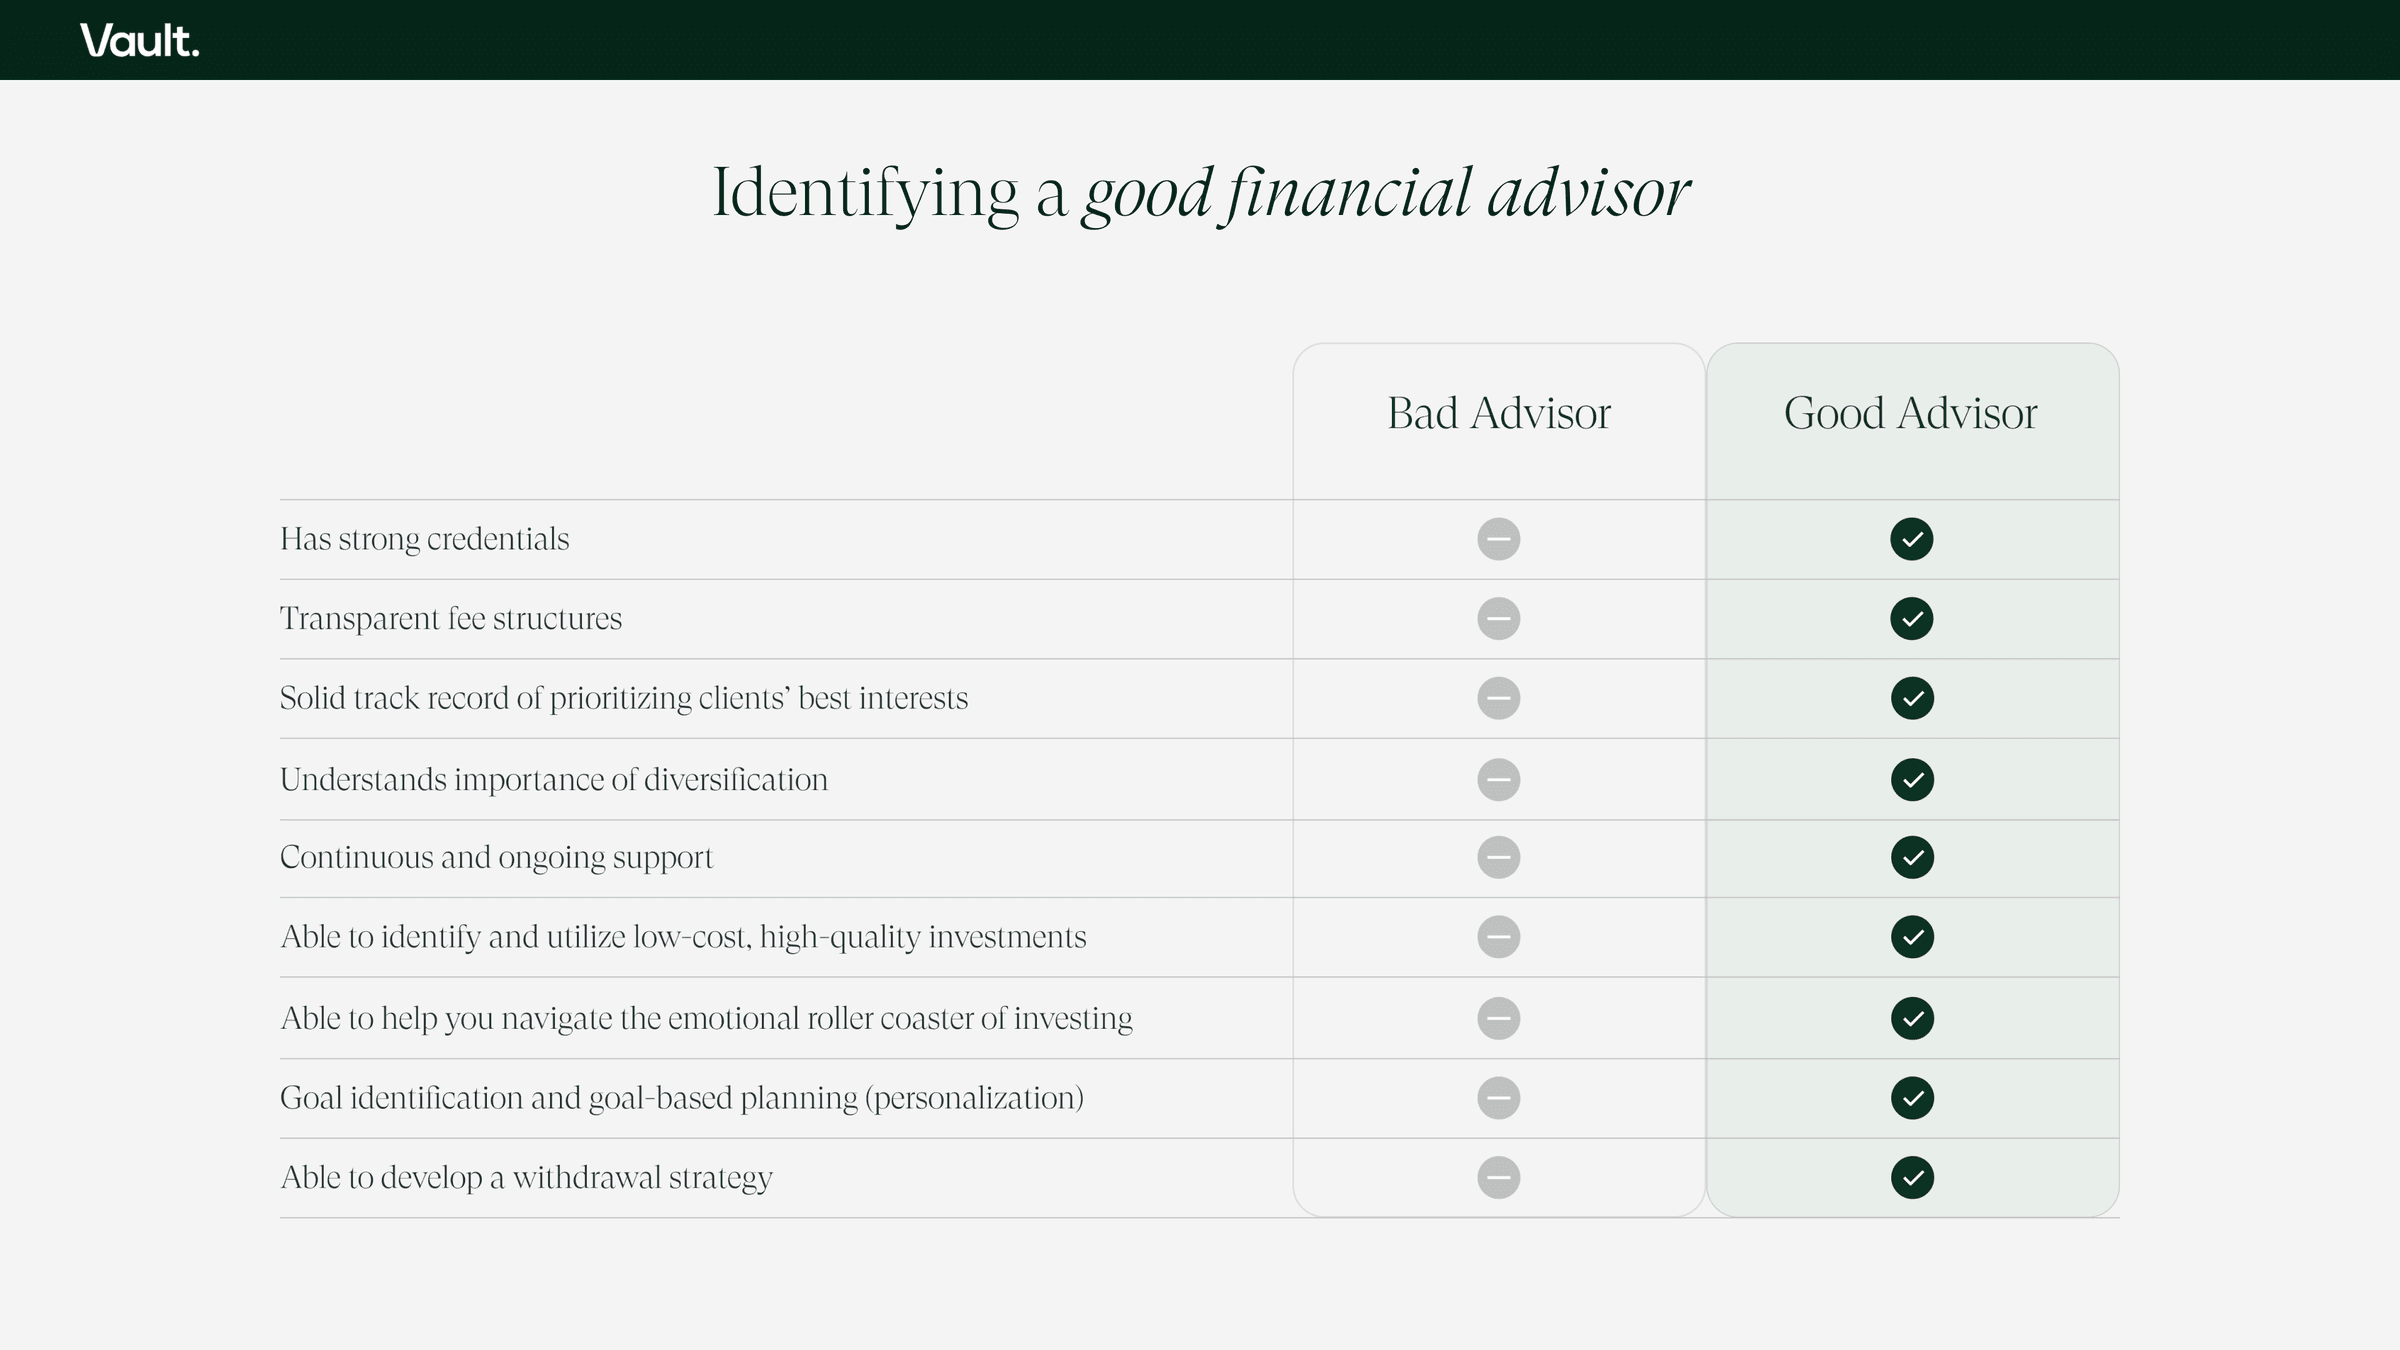
Furthermore, you need to ensure that you’re working with a true fiduciary; advisors who have a regulatory requirement to prioritize your best interests and are also incentivized by it, not by commissions. Another key consideration is their regulatory framework. The most stringent regulators in the UAE are ADGM’s FSRA and DIFC’s DFSA. Lastly, the more transparent they are, the less likely they are to be a shark. The UAE is unfortunately plagued by inconsistent advice, mis-selling of financial products, and lack of lasting relationships, all thanks to a swamp of bad actors or better yet, sharks. Last but not least, ensure you get their fees in writing.
Four questions separate firms in this market faster than any brochure: how the firm is paid, who regulates it, whose name is on the custody account, and what the total cost actually comes to. Our page on wealth management in Dubai sets out all four with Vault’s answers, and choosing a financial advisor in Dubai covers the individual you would work with — credentials, how that person is paid, and what a first meeting should produce.
Comparison of wealth management firms and companies in Dubai & UAE (2026)
Holborn Assets
- Investment opportunities - Investments and wealth management
- Added services - Financial planning, tax planning, insurance, employee benefits
- Regulating body - DFSA (Holborn Assets (DIFC) Limited, ref. F007545); UAE Central Bank (Holborn Assets Insurance Brokers, reg. 180)
- Fees - Not published
- Assets under management - USD 2bn+ (per Holborn’s website)
- Digital platform - Yes (Holborn App)
- Min. investment - Not published
Finsbury Associates
- Investment opportunities - Investments, pensions, savings plans and investment platforms
- Added services - Protection, estate planning, education planning, UK tax
- Regulating body - UAE Central Bank (FAEU Insurance Brokers, reg. 92); sister firm Finsbury Wealth (DIFC) Limited is regulated by the DFSA (ref. F006789)
- Fees - Not published
- Assets under management - Not published
- Digital platform - Online valuations portal; no app published
- Min. investment - Not published
Vault
- Investment opportunities - Customized diversified portfolios of global equities and bonds with access to private market opportunities and high-yield SmartCash accounts in USD, GBP and EUR paying daily interest (current rates are published on the page)
- Added services - Tax planning, retirement planning, estate planning
- Regulating body - ADGM FSRA
- Fees - Tiered from 1.25% on the first $100K, falling to 0.25% above $1M — a 0.78% blended rate on a $1M portfolio. No entry, exit, or product-based fees.
- Assets under management - Not published
- Digital platform - Yes
- Min. investment - Exclusive to individuals with a min. $100K in liquid net worth
AES International
- Investment opportunities - Investment management and wealth management
- Added services - Retirement and life-event planning, cross-border advice, multi-family office, employee benefits
- Regulating body - UAE Central Bank (AES Middle East Insurance Broker, licence 189) and DFSA (AES Financial Services, ref. F003476)
- Fees - Not published
- Assets under management - Not published
- Digital platform - Online client portal; no app published
- Min. investment - Typically USD 1M+ in investable assets (per AES’s website)
deVere Group
- Investment opportunities - Investment management, pensions (QROPS, SIPP, QNUPS), digital assets
- Added services - Tax planning, retirement planning, life and critical-illness insurance
- Regulating body - UAE Central Bank (deVere Acuma Insurance Brokers, reg. 190)
- Fees - Not published
- Assets under management - Approximately USD 14bn in client assets under advice, group-wide (per deVere’s website)
- Digital platform - Not published
- Min. investment - Not published
Century Financial
- Investment opportunities - Shares, ETFs, indices, commodities, currencies, treasuries and CFDs (40,000+ instruments across 125 markets, per Century’s website)
- Added services - Trading platforms; Century states it does not manage investments on behalf of clients
- Regulating body - UAE Capital Market Authority (CMA, formerly SCA), licence numbers 20200000028 and 301044
- Fees - Partly published: US cash equities at 1 cent a share, USD 4 minimum per transaction
- Assets under management - Not published
- Digital platform - Yes (Century Trader app)
- Min. investment - Not published
Ask us the four questions
How we are paid, who regulates us, whose name is on the custody account, and what the total cost comes to. A Vault advisor will answer all four in writing before you commit to anything.
Private wealth management in DubaiVault's published fee schedule
Conclusion
We can’t overstate how important it is to select a wealth management firm or company who is competent, ethical, and truly focused on your needs. A poor choice can lead to mis-selling, where advisors prioritize their commissions over your own best interest, resulting in potentially significant financial losses. This issue has plagued regions like the UAE, where many individual investors have lost confidence in the wealth management industry due to the prevalence of unscrupulous practices and unaligned incentives. A prime example of this is the widespread promotion of ‘Whole of Life Insurance’ in the UAE, where the wealth management firm makes a heavy upfront fee from the insurer to conduct the sale. In a majority of cases the policies are sold to clients seeking investments for their long-term future rather than an insurance policy
Sources
All accessed 22 October 2026.
- Holborn Assets, homepage and about page; DFSA public register, Holborn Assets (DIFC) Limited.
- Finsbury Associates, homepage and platforms; DFSA public register, Finsbury Wealth (DIFC) Limited.
- AES International, homepage and Smart Account; DFSA public register, AES Financial Services Ltd.
- deVere Group, overview.
- Century Financial, regulation and cash equities.
- Emirates NBD, Schedule of Fees and Charges on Portfolio Accounts, effective July 2026.
- Central Bank of the UAE, register of licensed financial institutions, August 2026 edition (insurance brokers).
Disclaimer: The comparisons and evaluations made in this article are based on information gathered from the public campaigns and available data of the competitor products as of the time of writing. While we strive to provide accurate and up-to-date information, we do not represent, warrant, or assert the completeness or accuracy of the data. Our insights and comparisons are made to the best of our knowledge and are not intended to speak on behalf of any company’s offering or to disparage any company’s reputation.
Please note that this article is provided for informational purposes only and should not be construed as solicitation, investment, legal, or financial advice. Readers are encouraged to conduct their own research and due diligence or consult with a professional advisor for specific advice tailored to their situation. We accept no liability for any direct or indirect loss or damage arising from any inaccuracies, omissions, or the use of information contained in this article.
Frequently asked questions
How do I choose between UAE wealth-management firms?
Apply four filters in order. (1) Regulation — FSRA, DFSA, or SCA on the public register. (2) Compensation — fee-only, no product commissions. (3) Custody — assets held in your name at a global custodian. (4) Process — written investment policy statement, formal review cadence, transparent reporting.Are international private banks better than local UAE firms?
Not automatically. Large international names have institutional infrastructure but often operate commission-driven sales models that misalign incentives. Several UAE-regulated fee-only fiduciaries offer better aligned advice with lower friction for UAE residents.What's the difference between "wealth management" and "private banking"?
Private banking typically sits inside a bank and combines investment, lending, and cash services with a relationship-manager-driven model. Wealth management can sit inside or outside a bank and focuses on holistic financial planning. Many HNW clients use both — private bank for specific functions, wealth manager for advice.Should I diversify across multiple firms?
Generally no for advice (consolidate), sometimes yes for custody (split across institutions). Multiple advisors usually produce conflicting recommendations and operational fragmentation; multiple custodians can provide useful institutional diversification for HNW estates.
From Vault
The structural picture behind this piece — regulators, minimums and total cost — is set out on the service pages.
- Wealth management in the UAEThree regulators, no state pension, and what that changes about a plan built here.
- Wealth management in DubaiHow to tell the firms apart, and what the total cost actually comes to.
- Finding a financial advisor in DubaiCredentials, how the individual is paid, and what a first meeting should produce.
- Wealth management in Abu DhabiWhat changes when your advisor is regulated inside the same free zone as your structures.
Related reading
More on UAE & GCC
- InsightBest Financial Advisors in Dubai & the UAE (2026)How to choose a financial advisor in the UAE in 2026: regulators, fiduciary standards, fee structures, and the firms worth meeting before you sign anything.
- InsightBest Investment Apps & Platforms in Dubai & the UAE (2026)The best investing apps and platforms for UAE residents in 2026 — compared on fees, asset coverage, regulation, and who each one actually suits.
- InsightChoosing Schools in the UAE: What HNW Families Should KnowHow HNW families choose schools in the UAE: regulators and inspection ratings, curricula, fee frameworks, and how to plan the cost of schooling and university across several children.